For most of your working life, the goal was simple: save as much as you reasonably could. Retirement flips that goal on its head. Now the question becomes how to turn decades of savings into income you can count on, potentially for 20, 30, or more years, without running out.
This is a different kind of planning than saving ever was. It involves coordinating several income sources at once, thinking through healthcare costs that tend to rise as we age, and protecting your purchasing power against inflation over a long retirement. None of this is one-size-fits-all, but there are some core ideas that apply to almost every household approaching or living in retirement.
We work with families across the Philadelphia area, including through the retirement planning seminars we run in Ambler, Doylestown, and Northampton, PA, and these are the same fundamentals we walk through with people getting ready to make this transition.
Key takeaways
- Retirement income planning is a distinct skill from accumulation. Growing savings and turning them into reliable income call for different strategies.
- Social Security, pensions, and portfolio withdrawals work best when coordinated together, not decided on separately.
- Healthcare costs, including gaps in Medicare coverage and the possibility of long-term care needs, deserve a place in your plan early, not as an afterthought.
- Inflation quietly erodes purchasing power over a long retirement, so a plan needs room to adjust over time.
- A written, coordinated plan reduces guesswork and gives you more confidence in your day-to-day spending decisions.
Turning savings into a reliable paycheck
During your working years, growth was the priority. In retirement, the priority shifts toward generating consistent income while still managing risk. That means thinking about your savings less as one big number and more as a series of income streams that need to work together over time.
A useful starting point is separating your expenses into categories: essential costs like housing, food, and insurance, and discretionary costs like travel or hobbies. Many retirees aim to cover essential expenses with more predictable income sources, such as Social Security or a pension, and use portfolio withdrawals for the more flexible parts of their budget. This approach can help reduce the stress of watching account balances move up and down with the market, since your core needs aren't as dependent on short-term performance.
How much you withdraw each year, and from which accounts, also affects how long your savings can last and how much you owe in taxes. These decisions are rarely simple, and they often benefit from a second set of eyes.
Coordinating Social Security, pensions, and portfolio withdrawals
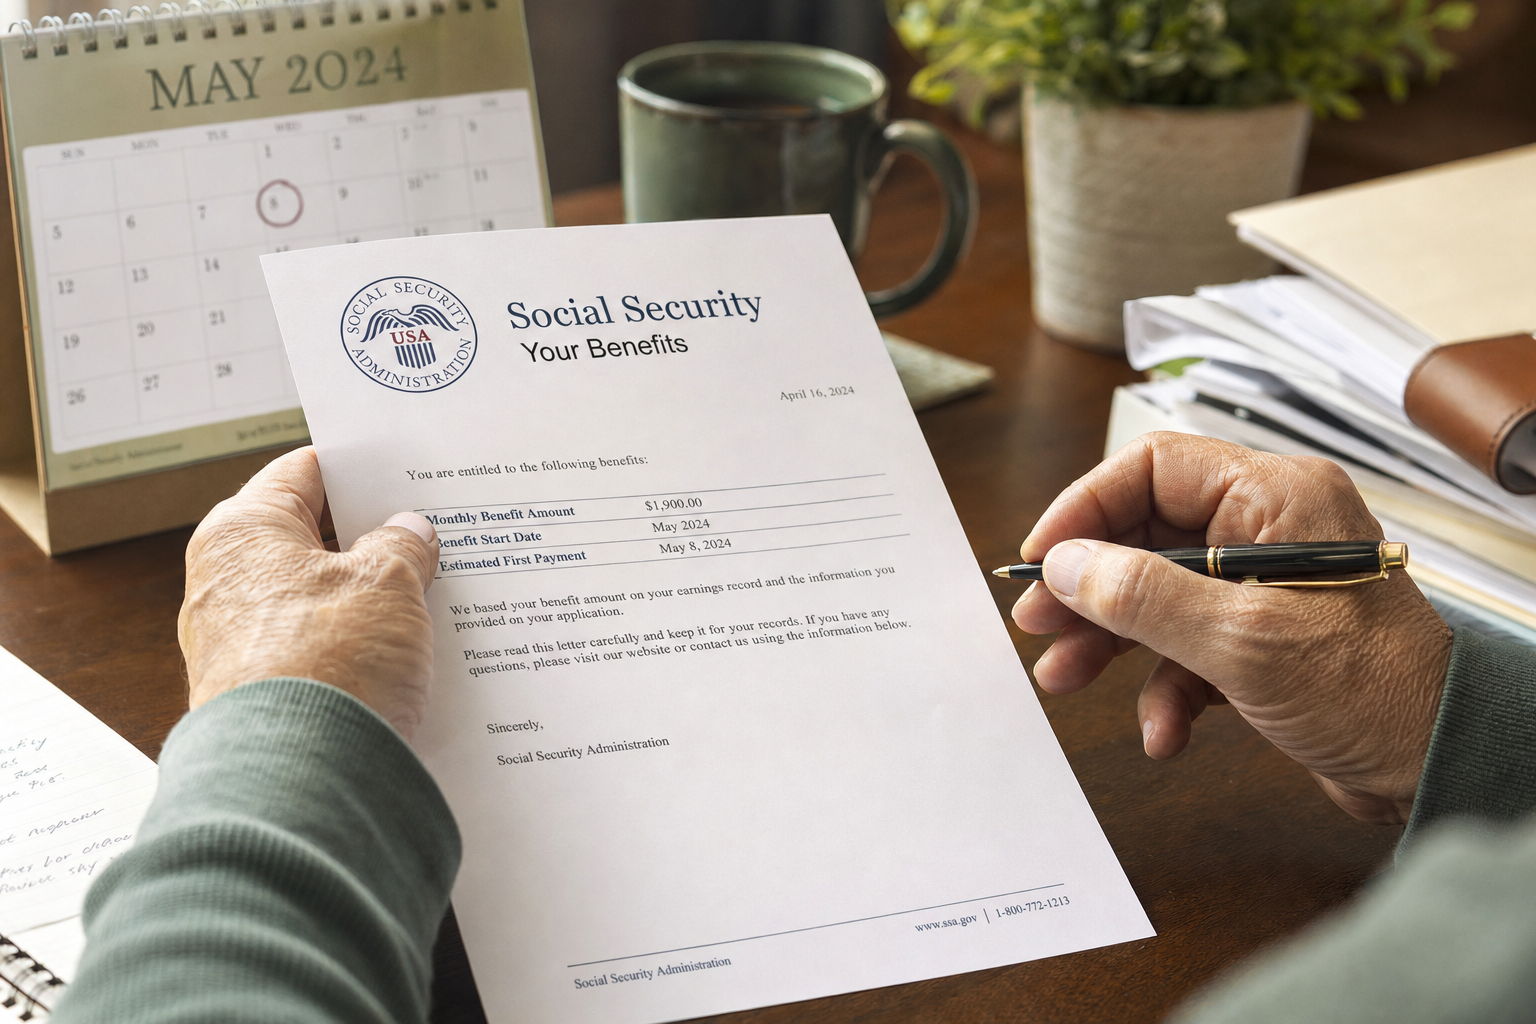
One of the most common mistakes we see is treating each income source as its own separate decision. When to start Social Security, how to take a pension (lump sum versus monthly payments, if that choice is available), and how much to withdraw from savings each year are closely connected decisions. A change in one can significantly affect the others.
For example, the age at which you start Social Security affects your monthly benefit for the rest of your life, and that decision may influence how much you need to draw from your investment accounts in the early years of retirement. Similarly, if you have a pension, understanding how it fits alongside Social Security and your other savings can help you avoid drawing down investment accounts faster than necessary.
The goal is a coordinated approach, where each income source has a role, rather than a collection of separate decisions made in isolation. This is one of the areas where working with a financial advisor tends to add the most value, since these choices are highly dependent on your specific circumstances, health, and goals.
Planning for healthcare costs, including Medicare gaps and long-term care
Healthcare is often one of the largest and least predictable expenses in retirement. Medicare provides a foundation of coverage for most retirees, but it does not cover everything. There can be gaps in coverage for things like certain out-of-pocket costs, and Medicare generally does not cover long-term custodial care, such as an extended stay in a nursing home or ongoing in-home care.
Because these costs can be significant and are hard to predict in advance, it's worth thinking through, in general terms, how you would cover a major healthcare expense or a long-term care need if one arose. Some people build this into their overall savings, others look at insurance-based strategies, and the right approach depends on your health, family history, and overall financial picture. There isn't a single right answer here, which is exactly why it deserves a conversation with a professional who understands your full situation.
Protecting your income from inflation
A dollar today will not buy as much 15 or 20 years from now. Over a retirement that could last several decades, even modest inflation can meaningfully reduce your purchasing power if your plan doesn't account for it.
This is one of the reasons a retirement income plan usually needs a growth component, not just safety and stability. Keeping all of your savings in very conservative, low-growth vehicles may feel safer in the short term, but it can leave you vulnerable to rising costs later in retirement. On the other hand, taking on too much risk can expose your income to market swings you're not comfortable with. Finding the right balance, and revisiting it as your circumstances change, is part of building a plan that's meant to hold up over time.
Common mistakes to avoid
- Making Social Security, pension, and withdrawal decisions separately instead of together
- Underestimating healthcare and potential long-term care costs
- Assuming a conservative portfolio automatically means a safer retirement, without accounting for inflation
- Waiting until retirement is already underway to build a coordinated income plan
- Not revisiting the plan as life circumstances, health, or the economy change
When to talk with us
Every family's situation is different, and the right combination of income sources, timing, and investment approach depends on your specific goals, health, and financial picture. If you're within a few years of retirement, or already retired and want a second look at how your income sources fit together, it may be a good time to schedule an introductory consultation with us. We also invite people to attend one of our educational retirement planning seminars in Ambler, Doylestown, or Northampton, PA, if you'd like to learn more in a group setting before meeting one-on-one.
Frequently asked questions
When should I start taking Social Security? There isn't a single right age for everyone. It depends on your health, other income sources, and overall retirement plan. This is worth discussing with an advisor who can look at your full picture.
Do I need a separate plan for healthcare costs in retirement? It's wise to think about healthcare, including potential gaps in Medicare coverage and the possibility of long-term care needs, as part of your overall retirement income plan rather than as an afterthought.
How much should I withdraw from my savings each year? This depends on your total savings, other income sources, expenses, and time horizon. A coordinated plan can help you find a withdrawal approach suited to your situation.
Is a pension lump sum or monthly payments better? It depends on factors like your health, other income sources, and how comfortable you are managing the funds yourself. There's no universal answer.
How does inflation affect my retirement plan? Over a long retirement, rising costs can reduce what your income actually buys. Plans generally need some growth component to help offset this over time.
Can I change my retirement income plan after I've started it? Yes. A retirement income plan should be reviewed periodically and adjusted as your health, goals, or the broader economic environment change.
What's the difference between saving for retirement and planning retirement income? Saving focuses on growing your assets. Income planning focuses on turning those assets into a reliable stream of income while managing risk, taxes, and longevity.
Do I need a financial advisor to build a retirement income plan? While some people manage this on their own, many find value in working with an advisor who can help coordinate the moving pieces and tailor a plan to their specific circumstances.
What if I'm already retired but never built a coordinated plan? It's not too late. Many retirees benefit from a mid-retirement review to make sure their income sources are working together and their plan still fits their needs.
How do I get started? A good first step is scheduling an introductory consultation with us, or attending one of our local retirement planning seminars, so we can understand your situation and talk through your options.
This material is for educational purposes only and is not intended as personalized investment, tax, or legal advice. Every individual's situation is different, and you should consult with a qualified professional regarding your specific circumstances before making financial decisions.
Securities offered through LPL Financial, Member FINRA/SIPC. Investment advice offered through Global Retirement Partners, LLC, dba CDS Wealth Management Inc., a registered investment advisor and separate entity from LPL Financial.